10 Sep 2026 Should We Stay or Should We Reno?
Mortgages are back in the headlines with rates climbing slightly back up after rising Treasury yields and some renewed inflation pressure. And at the same time, median existing home prices are hitting new highs. There was some hope earlier this year that a 30-year mortgage may slide back under 6% but over the year, a 30-year mortgage rate is back up to about 6.8% as I write this brief. (Also, you should probably go ahead and put on The Clash as your reading background music as I evaluate should I stay or should I go?)
Below is a chart from the Federal Reserve showing what interest rates looked like over the last 10 years for 30-year mortgages, 15-year mortgages, and Home Equity Lines of Credits (HELOCs). This depicts a monthly average over the last 10 years. The 15-year mortgage consistently has the lowest rate (aside from a short blip in 2022), saving about .67% from a 30-year mortgage. The HELOC has the highest rate.

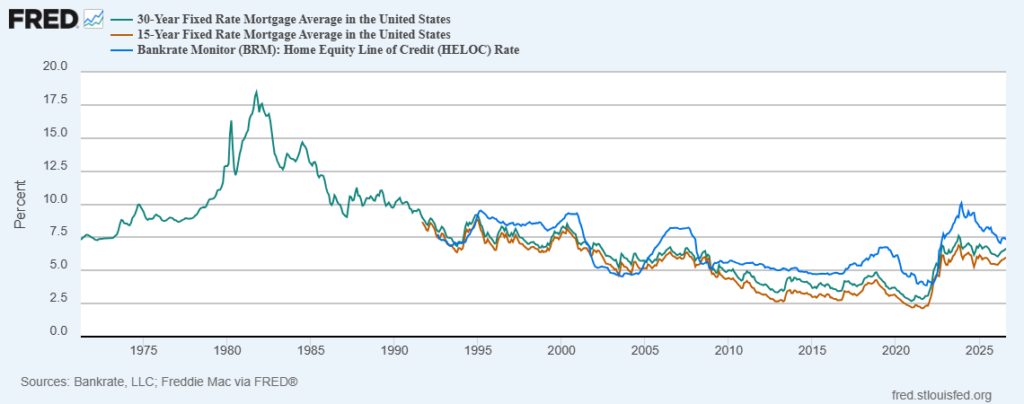
As you can see, current 30-year mortgage rates sit almost double where we were 10 years ago, and almost triple from lows in 2020-2021. If we zoom out further to show all-time history below, you’ll see we’ve been here before – several times. I do not have a crystal ball to show where we’ll go from here, but I do know that buying a home is not strictly an investment, and sometimes you just have to make the most reasonable decision for the data currently before you.
FRED Source Info 1
I included the blue HELOC line here as that is a potential source of funds that we are considering as we weigh whether to start a home search or consider an addition and renovation of our current home. Many current homeowners may feel somewhat stuck in their current homes because of favorable interest rates from the super low 2019-2021 time frame, when refinancing or buying kept lenders very busy. We purchased our home in 2019 then refinanced a few years later to reduce our rate even more. Prospective home buyers now face home prices continuing to rise without relief from interest rates, making the same monthly payment buy less house as time marches on during their home search.
As with many aspects of personal finance, it can be tempting to look back on a prior home purchase with scrutiny and a lot of if only’s. We bought our house before having kids, and have many ideas about how to make our home work better for us now that we have two boisterous boys. Sometimes it is tempting to wonder if only we had stretched ourselves and found a bigger home then, we wouldn’t have to give up our inexpensive interest rate now, or have to add onto our house to keep up with our family’s wants and needs. If only we bought in a different neighborhood that appreciated quicker than ours. If only, if only! Prices in Raleigh continue to grow at a pace above national levels. Hindsight is 20/20.
Any big decision has a financial component and non-financial, and part of our job in the financial planner seat is to help you consider your choices.
If you find yourself in a similar situation, some financial questions to consider include:
- Will you finance or pay cash? What kind of loan is best for your end goal? We encourage shopping for multiple rate offers and making sure you understand the terms of your loan, and how that fits into your broader financial picture.
- What are other timeline factors at play? Does this move or home project occur around any retirement or job change timeline? Or becoming empty nesters? How might those impact cash flow?
- If paying cash, will you spend from investment savings, bank savings, or funded via cash flow? What is the impact on your financial plan from withdrawing funds to purchase or renovate? Are you willing to make a tradeoff (like pushing out a retirement date, for example) to counter the impact of a withdrawal? Are there taxable impacts from pulling from portfolio assets?
- If financing with any sort of line of credit or adjustable-rate mortgage, do you have a plan of paying down the debt in a way that does not absolutely rely on interest rates dropping in the future?
- How much will cash flow be impacted by additional debt or a larger property?
- Do you have sufficient disability and life insurance to protect yourselves?
Then there are the equally important lifestyle questions:
- What is the potential disruption to my family? Would a renovation require moving out for a period during some construction? Will kids feel unsettled?
- Does a move change our school district? How much does the school zone impact the price point for a new home?
- If we go to the work of doing a renovation, how much wiggle room do we want to build into the budget for overages due to inflationary changes for supplies or labor, or project expansion as we go along? We hear it all the time! If we’re doing this work, might as well get the [insert any home improvement] that I really wanted. I say that without any judgment – it’s a reality of renovations.
- How to minimize risk when buying a new home? What if an inspection uncovers something that requires us to rethink the purchase, or spend more on repairs?
- What will our family’s wants and needs look like in 5, 10, 15 years?
From a purely financial perspective, our monthly carrying cost would likely be much lower after a renovation than if we were to buy a new house, because the interest rate differential really starts to add up. We have some savings earmarked for home improvement/purchase, plus some additional equity in our home available via a line of credit if we do want to renovate.
Or we could use those same savings to help with a down payment on a new home. Even if we managed to keep the same loan amount (and we wouldn’t), our minimum monthly payment jumps by $500 just with the higher interest rate. Our monthly principal and interest payment on a 6.7% 30-year mortgage would increase by ~$323/month with every $50k step up in price point. Plus the additional property taxes and insurance for a more expensive property. But again, few decisions are purely financial in nature. Perhaps it is worth it to our family to forego a 2021 interest rate to skip living through a renovation in an already very chaotic and full stage of life? Time will tell.
Our personal answer to should we stay or should we go changes depending on the day. These questions and example calculations are infinitely helpful to keep perspective and rank our priorities as Wesley and I discuss our options. I did not come to any conclusions by the end of writing this, but I hope sharing the thought process is helpful. Stay tuned to see what we decide over the coming months….
As a bonus for making it to the end of today’s brief, Ryan and Emily evaluated this similar question several years ago in their episode of Love it or List It!
The content above is for informational and educational purposes only. The links and graphs are being provided as a convenience; they do not constitute an endorsement or an approval by Beacon Wealthcare, nor does Beacon guarantee the accuracy of the information.
- Bankrate, LLC, Bankrate Monitor (BRM): Home Equity Line of Credit (HELOC) Rate [BRMHELOC01], retrieved from FRED, Federal Reserve Bank of St. Louis; https://fred.stlouisfed.org/series/BRMHELOC01, .
Freddie Mac, 30-Year Fixed Rate Mortgage Average in the United States [MORTGAGE30US], retrieved from FRED, Federal Reserve Bank of St. Louis; https://fred.stlouisfed.org/series/MORTGAGE30US, .
Freddie Mac, 15-Year Fixed Rate Mortgage Average in the United States [MORTGAGE15US], retrieved from FRED, Federal Reserve Bank of St. Louis; https://fred.stlouisfed.org/series/MORTGAGE15US, . ↩︎
